
Introduction
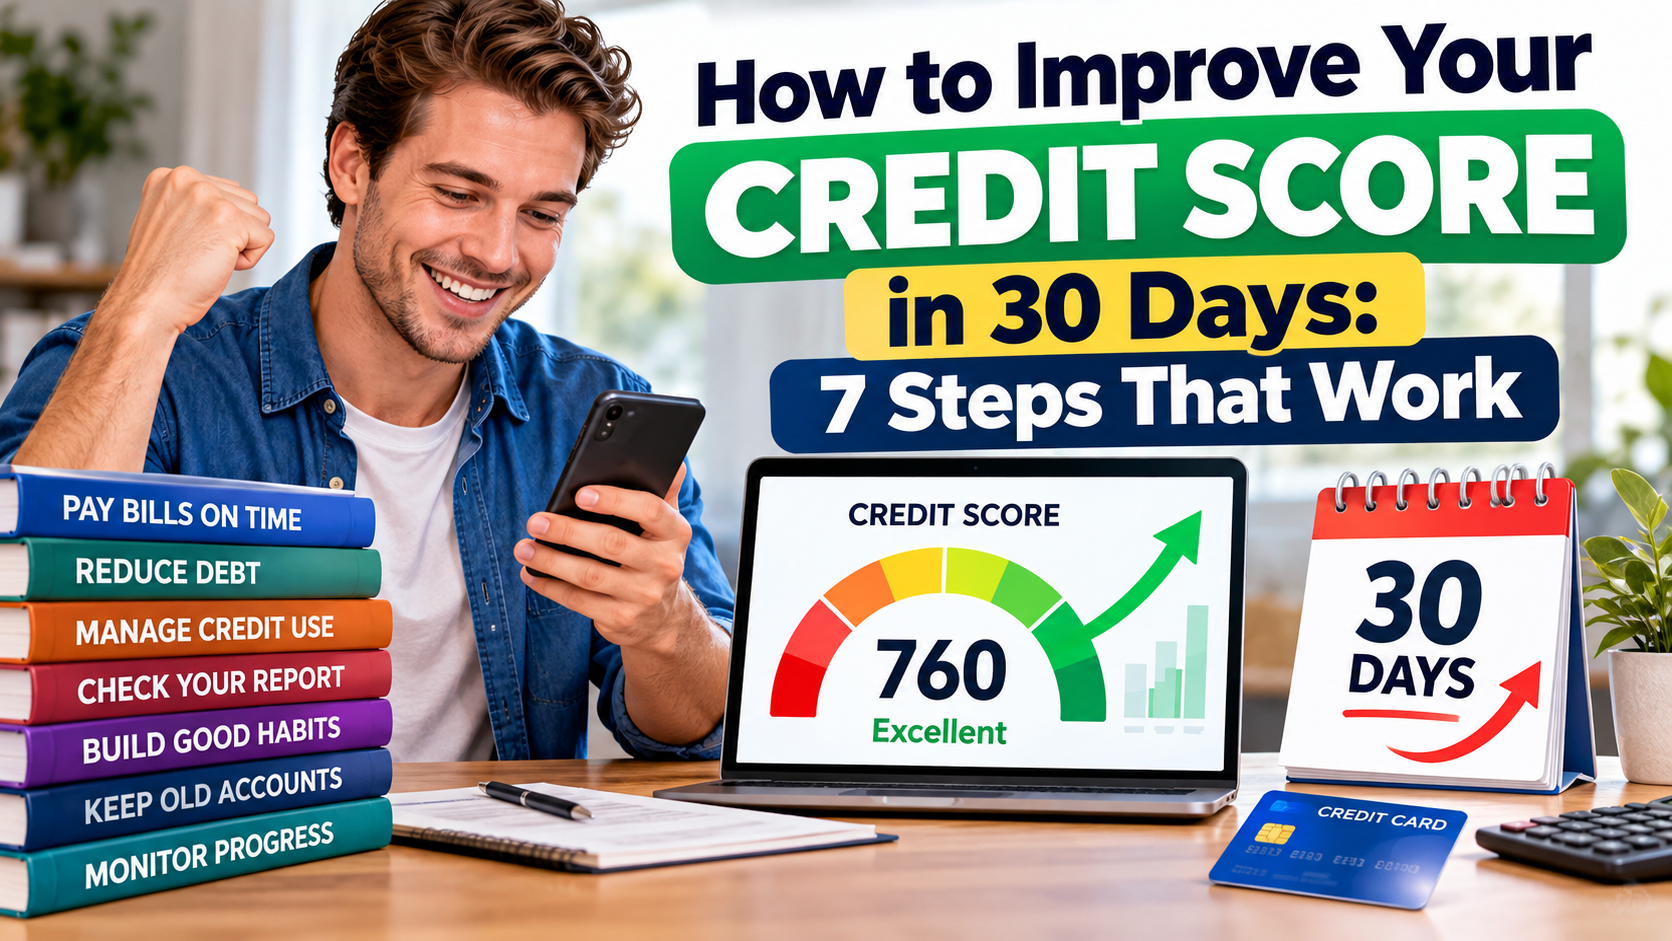
How to Improve Your Credit Score in 30 Days starts with knowing what is holding your score back. A low credit score can make borrowing more expensive and make it harder to get approved for credit—but the right steps can help you start making progress within a month.
Whether your score is low because of high credit card balances, missed payments, or inaccurate information, there are practical actions you can take now to improve your credit profile.
This guide covers 7 practical steps to improve your credit score in 30 days, without promising an overnight fix or a specific number of points.
What Is a Credit Score?
A credit score is a number that represents how you have managed credit in the past. Lenders use credit scores, along with other information, to assess how likely you are to repay borrowed money.
Your score can be influenced by factors such as:
- Payment history
- Credit utilization
- Length of credit history
- New credit applications
- Types of credit accounts
A higher score can make it easier to qualify for credit and may help you access better borrowing terms, although lenders use different scoring models and requirements.
What Is Credit Utilization?
Credit utilization is the percentage of your available revolving credit that you’re using.
For example, if your credit card limit is $2,000 and your balance is $600, your credit utilization is 30%.
A lower utilization rate is generally better for your credit profile. If your balances are high, paying them down can help once your lender reports the updated balance.
How to Lower Your Credit Utilization
- Pay down your credit card balances.
- Make an extra payment before your statement closes when possible.
- Avoid maxing out your available credit.
- Don’t take on unnecessary new debt.
The Credit Score Timing Map: Why When You Pay Matters
One of the most overlooked parts of improving your credit score is timing.
Your credit card has several important dates, and they are not necessarily the same:
- Statement closing date: The billing cycle ends and your statement is generated.
- Payment due date: The date your payment must be received to avoid being late.
- Credit-reporting date: The date your card issuer sends account information to a credit bureau.
These dates can affect what balance appears on your credit report.
Here’s a simple example
Imagine you have a credit card with:
- Credit limit: $2,000
- Current balance: $1,200
- Statement closing date: September 18
- Payment due date: October 13
If your issuer reports the $1,200 balance around the statement closing date, your credit report could show 60% utilization even if you intend to pay the entire balance before October 13.
If you reduce the balance before the statement closes, the amount reported may be lower.
That’s why someone can technically pay their credit card bill on time every month and still temporarily show high utilization on their credit report.
Your 30-day strategy
If your goal is to reduce your reported utilization:
- Find your statement closing date.
- Check your current balance.
- Calculate your utilization.
- Make a payment before the statement closes when possible.
- Check your credit report after the issuer has had an opportunity to report the new balance.
The important point is that the payment due date and the reporting cycle serve different purposes.
The due date helps you avoid being late. The statement/reporting cycle can determine what balance appears on your credit report.
7 Pratical Ways to Improve Your Credit Score in 30 Days
1. Pay Your Bills on Time
Payment history is one of the most important factors used in credit scoring. Missing payments can hurt your score, while consistently paying on time helps establish a stronger credit history.
Practical steps
- Pay at least the minimum amount due before the deadline.
- Set up automatic payments for your credit accounts.
- Set payment reminders several days before each due date.
- If you have missed a payment, bring the account current as soon as possible.
- Contact your creditor if you’re struggling to make a payment.
A payment that is 30 or more days late can be reported to the credit bureaus and may significantly affect your score.
2. Pay Down Your Credit Card Balances
One of the quickest areas to focus on is your credit utilization ratio, which measures how much of your available revolving credit you’re using.
For example, if your credit limit is $2,000 and your balance is $1,000, your utilization is 50%.
Lower utilization is generally better for your credit score. Experts commonly recommend keeping utilization below 30%, while people with the highest scores often have utilization below 10%.
Practical steps
- Pay down cards with the highest balances first.
- Make an extra payment before your statement closes.
- Avoid charging new purchases to a card you’re trying to pay down.
- Don’t max out your available credit.
- Continue making at least the required payment on every account.
If your lender reports a lower balance after you make a payment, your score may change after the credit report is updated. This can sometimes happen within 30 to 45 days.
The “One-Bad-Card” Problem: Why Total Utilization Isn’t the Whole Story
When people calculate credit utilization, they often look only at their total balances.
For example:
- Card A: $900 balance / $1,000 limit
- Card B: $100 balance / $1,000 limit
Your total balance is $1,000 against $2,000 of available credit, giving you 50% overall utilization.
But there’s another number worth paying attention to: utilization on each individual card.
A single card that is close to its limit can deserve attention even when your overall utilization appears more manageable.
What to check
For every revolving credit account, calculate:
Card balance ÷ Card credit limit × 100 = Individual utilization
Then create a simple list:
| Card | Balance | Limit | Utilization |
|---|---|---|---|
| Card A | $900 | $1,000 | 90% |
| Card B | $100 | $1,000 | 10% |
| Card C | $200 | $2,000 | 10% |
This makes it easier to identify which account needs attention first.
If you have limited money available for debt repayment, don’t automatically divide the money equally among every card. First identify the accounts with the highest utilization and consider how reducing those balances would affect your overall credit profile.
Remember that utilization is only one part of your credit score, and there is no universal balance or percentage that guarantees a particular score increase.
3. Check Your Credit Report for Errors
An inaccurate credit report can hold your score back. Errors can include accounts that don’t belong to you, incorrect balances, inaccurate payment information, duplicate debts, or incorrect account status.
Practical steps
- Get your credit reports from the relevant credit reporting agencies.
- Check your account balances and payment history.
- Look for unfamiliar accounts or transactions.
- Check that closed accounts are correctly reported.
- Dispute inaccurate information with the credit reporting company and the company that supplied the information.
If an error is corrected, the change can be reflected in your credit report and potentially affect your score. Credit reporting companies generally have 30 days to investigate a dispute, although some cases can take up to 45 days.
The Two-Party Credit Report Dispute Strategy
Found an error? You may need to contact two parties:
- The credit reporting company.
- The company that supplied the information.
Before disputing:
- Save a copy of the error.
- Gather supporting documents.
- Explain exactly what is wrong.
- Submit the dispute to the relevant parties.
- Keep copies of your documents and responses.
Don’t dispute information simply because it is negative. Dispute information because it is inaccurate or incomplete.
4. Avoid Applying for New Credit
Applying for several credit cards or loans within a short period can result in multiple hard inquiries and may negatively affect your credit profile.
If you’re trying to improve your score within 30 days, avoid unnecessary credit applications.
Practical steps
- Don’t apply for several credit cards at once.
- Only apply for credit you actually need.
- Check eligibility requirements before applying.
- Avoid opening new accounts simply to increase your available credit.
- Focus on managing your existing accounts first.
Does the 15/3 Credit Card Hack Really Work?
You may have heard of the 15/3 credit-card hack, which recommends making payments 15 days and 3 days before your due date.
But there is no universal credit-scoring rule requiring this schedule.
The useful part is understanding when your card issuer reports your balance.
If you reduce your balance before the reporting date, a lower balance may appear on your credit report.
Focus less on the “15/3” formula and more on your card’s actual reporting cycle.
There is an exception for certain loan rate-shopping situations, where multiple inquiries made within a focused period may be treated differently by scoring models.
5. Pay Down Existing Debt
Reducing your outstanding debt can improve your overall credit profile, particularly when high credit card balances are contributing to high utilization.
Simply transferring debt between cards does not eliminate what you owe. The goal is to reduce the amount of debt you actually carry.
Practical steps
- List your credit card balances and interest rates.
- Choose a repayment strategy you can maintain.
- Put extra money toward high-interest debt.
- Avoid adding unnecessary purchases to your cards.
- Continue making the minimum payment on other accounts while paying extra toward your priority debt.
6. Keep Older Credit Accounts Open When Appropriate
The length of your credit history can contribute to your credit profile. Closing an older credit card may also affect your available credit and utilization.
That doesn’t mean you should keep every account open. If a card has expensive fees or creates financial problems, closing it may still make sense. But don’t close an older account simply because you’re not using it without considering the potential effect on your credit profile.
Practical steps
- Review the annual fee and other costs before deciding.
- Avoid closing an older account unnecessarily.
- Keep accounts you can manage responsibly.
- Don’t use an old card simply to create debt.
- If you keep a card open, monitor it for unauthorized activity.
7. Get Help if You’re Struggling With Payments
If you can’t keep up with your bills, waiting until you miss several payments can make the situation harder.
Contacting your creditors early may give you access to hardship or payment-assistance options. A legitimate credit counselor may also help you create a debt-management plan.
Practical steps
- Contact your creditor before missing a payment.
- Ask whether hardship assistance is available.
- Explain your financial situation honestly.
- Create a realistic repayment budget.
- Research any credit counselor or debt-relief company before paying for its services.
Be cautious of companies that promise to remove accurate negative information from your credit report. Accurate negative information generally cannot simply be removed because you want it gone.
You may see an improvement in a month, especially if high credit card balances, missed payments, or inaccurate information are affecting your score. However, there is no guaranteed number of points you can gain in 30 days.
Experian explains that the impact of these actions depends on your individual credit profile. Learn more from Experian about improving your credit score in 30 days
How Much Can Your Credit Score Improve in 30 Days?
There is no fixed number of points that everyone can gain in 30 days.
Your potential improvement depends on what’s currently affecting your score. Someone with high credit card utilization may see a change after paying down a large balance, while someone rebuilding from serious late payments may need considerably more time.
For example, paying down a credit card can affect your score once the lower balance is reported, which may take around 30 to 45 days depending on the lender’s reporting cycle.
Your 30-Day Credit Score Diagnostic
Before trying to improve your score, identify what’s actually hurting it.
| What you find | Focus on |
|---|---|
| High card utilization | Reduce balances |
| Incorrect late payment | Dispute it |
| Unknown account | Investigate and dispute |
| Incorrect balance | Dispute it |
| Several recent applications | Avoid unnecessary applications |
| No obvious problems | Maintain good payment habits |
Instead of asking:
“How can I gain 50 points?”
Ask:
“What is currently hurting my credit profile?”
Fixing the biggest problem first gives you a more targeted strategy.
The key is to focus on changes you can actually control rather than chasing a specific number.
What Can Improve Your Credit Score the Fastest?
If you’re working with a 30-day deadline, prioritize these actions:
- Pay down high credit card balances.
- Make every payment on time.
- Check your credit reports for errors.
- Dispute inaccurate information immediately.
- Avoid unnecessary new credit applications.
- Reduce existing debt where possible.
- Keep your credit accounts under control.
These actions don’t guarantee an immediate increase, but they address several factors that can influence your credit score.
A Realistic 30-Day Credit Improvement Plan
Week 1: Check Your Credit
Start by checking your credit reports and identifying what’s hurting your score.
Look for:
- High credit card balances
- Missed payments
- Incorrect account information
- Unfamiliar accounts
- Collection accounts
- Recent credit applications
Week 2: Reduce Your Balances
Use available funds to pay down your highest credit card balances. Prioritize accounts with high utilization.
Week 3: Fix Errors and Stop New Applications
Submit disputes for inaccurate information and avoid applying for unnecessary credit while you’re rebuilding your score.
Week 4: Keep Everything Current
Make every payment on time, keep balances low, and monitor your accounts for updates.
Remember that credit reporting does not happen instantly, so some changes may not appear until your lender reports your updated information.
A credit score is a number that represents how you have managed credit in the past. Lenders use credit scores, along with other information, to assess how likely you are to repay borrowed money. The CFPB explains that different lenders may use different credit scoring models and scores. Learn more about credit scores from the CFPB
Frequently Asked Questions on How to Improve Your Credit Score in 30 Days
Can I really improve my credit score in 30 days?
Yes, some people may see an improvement within 30 days, particularly after paying down high credit card balances or correcting inaccurate information. However, there is no guaranteed increase for everyone.
What is the fastest way to improve my credit score?
Paying down high credit card balances, making payments on time, and correcting inaccurate information can be among the quickest ways to address factors affecting your score.
Will paying off a credit card raise my credit score?
It can. Paying down a credit card can reduce your credit utilization, which may improve your score once the lower balance is reported.
Does checking my credit report lower my score?
Checking your own credit report does not create the same type of hard inquiry associated with applying for new credit and does not hurt your score.
How long does it take to rebuild bad credit?
It depends on the severity of the negative information and your current credit history. Some changes can happen relatively quickly, while rebuilding a strong credit profile after serious problems can take months or years.
Conclusion on How to Improve Your Credit Score in 30 Days
Improving your credit score in 30 days is possible, but there are no guaranteed overnight fixes. Start by paying your bills on time, reducing credit card balances, checking your credit report, correcting errors, and avoiding unnecessary new debt.
You may see changes after your creditors update your information, but building strong credit requires consistent habits beyond the first 30 days.
The goal isn’t just to raise your score quickly. It’s to build a credit history that stays strong over time.